
Categories
Home BuyersPublished October 16, 2026
Temporary Buydown in Pittsburgh: 3-2-1 vs 2-1 Buydown, Explained With Real Math
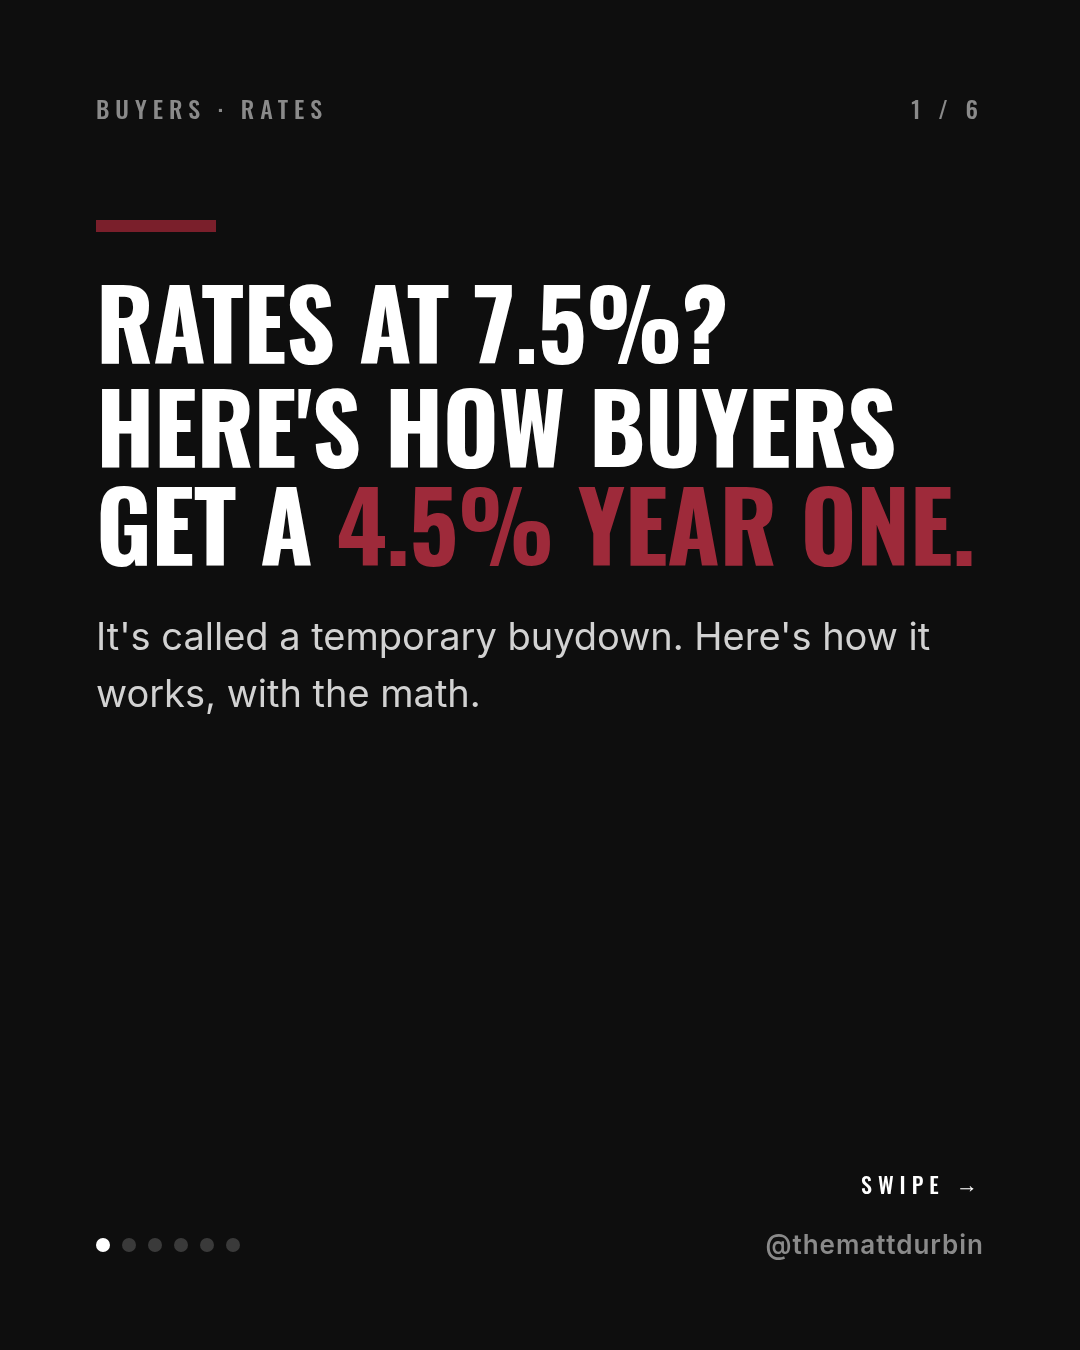
Short answer: A temporary buydown lowers your mortgage rate for the first one to three years. Then it steps up to the full rate. The cost is paid up front at closing, and a seller can pay it. With Pittsburgh mortgage rates near 7.5%, run a buydown next to a price cut before you pick one.
What is a temporary buydown?
A temporary buydown is a way to make the first years of a mortgage cheaper.
- Your rate starts lower.
- It goes up a step each year.
- It lands at your full note rate and stays there.
- The money to cover the gap is paid at closing and held in an account.
- Each month, that account pays the difference.
There are two common types:
- 3-2-1 buydown: 3% off in year one, 2% off in year two, 1% off in year three.
- 2-1 buydown: 2% off in year one, 1% off in year two.
After the buydown ends, you pay the full rate unless you refinance.
Why buydowns matter right now
Rates have not come down much. The chief economist at NAHB says 7.5% may be the new normal for a while. We covered that in Are 7.5% Mortgage Rates the New Normal?
So the better question is not "when will rates drop?" It is "how do I make the first few years work?" A buydown is one answer.
The math: a $300,000 loan at 7.5%
Principal and interest only. For illustration only. Not a loan offer or commitment to lend. Rates, payments, and terms depend on credit, income, loan program, and lender approval, and can change without notice. Buyers may need to qualify at the full note rate. Talk to a licensed lender for details.
Full payment at 7.5%: $2,097.64/mo
3-2-1 buydown
- Year 1 at 4.5%: $1,520.06/mo (saves $577.58/mo)
- Year 2 at 5.5%: $1,703.37/mo (saves $394.27/mo)
- Year 3 at 6.5%: $1,896.20/mo (saves $201.44/mo)
- Years 4 to 30 at 7.5%: $2,097.64/mo
- Total cost: $14,079.48
2-1 buydown
- Year 1 at 5.5%: $1,703.37/mo (saves $394.27/mo)
- Year 2 at 6.5%: $1,896.20/mo (saves $201.44/mo)
- Years 3 to 30 at 7.5%: $2,097.64/mo
- Total cost: $7,148.52
The total cost is just the monthly savings added up. That is the money that has to be paid at closing.
For buyers: how to use a buydown
A buydown helps most when the first years are the tight ones.
- New job or raise coming. Lower payments early can bridge the gap.
- First-time buyers. Moving costs, furniture, and repairs hit in year one. A lower payment helps.
- Plan to refinance. If rates fall, you may refinance. Ask your lender what happens to any buydown money left over.
Things to check first:
- Can you afford the full payment? Many lenders qualify you at the full note rate, not the year-one rate. Make sure year four works in your budget.
- Ask who pays. You can pay it. A seller can pay it. A builder may pay it.
- Ask your lender. Rules differ by loan type and lender. Get their numbers before you write the offer.
Buyers looking in Allegheny County, Washington County, Butler County, Beaver County, and Westmoreland County can all ask for this. It is not tied to one town.
For sellers: a buydown vs a price cut
The Pittsburgh market is flattening. Homes are sitting a bit longer, and buyers are asking for more. Sellers are more open to credits.
When a buyer's payment is the problem, a price cut may not fix it much. A buydown goes straight at the payment.
Before you cut the price, run both:
- Price cut: lowers the loan a little for all 30 years.
- Seller-paid buydown: lowers the payment a lot for the first one to three years.
- Your net: look at what you walk away with in each case.
A seller credit for a buydown can also keep your list price where it is. That can matter for how the home looks next to other sales on your street.
If your home has been sitting, check the other pricing mistakes too. See 4 Pricing Mistakes in a Flattening Pittsburgh Market.
How a buydown fits into an offer
Here is the order most deals follow:
- Talk to a lender first. Ask if your loan allows a buydown and how they qualify you.
- Get both numbers. Ask for your payment with a buydown and with a lower price.
- Write it into the offer. The buydown is usually asked for as a seller credit toward closing costs.
- Check the cap. Loans limit how much a seller can pay toward your costs. Your lender will know the limit.
- Close. The buydown money goes into an account, and your lower payment starts with your first bill.
Where this shows up around Pittsburgh
Buydowns can help in any part of the region where payments feel tight. Buyers ask about them in places like:
- Allegheny County: Pittsburgh, Mt. Lebanon, Upper St. Clair, Bethel Park, Ross, McCandless
- Washington County: Peters Township, Canonsburg, Cecil
- Butler County: Cranberry Township, Butler, Adams Township
- Beaver County: Hopewell, Center Township, Beaver
- Westmoreland County: Greensburg, North Huntingdon, Murrysville
Common questions
What is a 3-2-1 buydown?
It lowers your rate by 3% in year one, 2% in year two, and 1% in year three. In year four you pay the full rate. On a $300,000 loan at 7.5%, it costs about $14,079.48 (example only).
What is a 2-1 buydown?
It lowers your rate by 2% in year one and 1% in year two. In year three you pay the full rate. On a $300,000 loan at 7.5%, it costs about $7,148.52 (example only).
Who pays for a temporary buydown?
The cost is paid up front at closing. The buyer, the seller, or a builder can pay it. A seller-paid buydown is a common ask in a flattening market.
Is a buydown better than a price cut?
It depends on the buyer. A buydown lowers the payment more in the early years. A price cut lowers it a little for the whole loan. Run both next to each other.
Do I qualify at the lower rate?
Often no. Many lenders qualify you at the full note rate. Ask your lender before you make an offer.
What happens if I refinance early?
Ask your lender. Rules on leftover buydown money differ by lender and loan type.
Matt Durbin | eXp Realty
(412) 998-8896 | Broker: (888) 397-7352
MAD.Homes
Matt Durbin
Team Leader | Matt Durbin Team | eXp Realty
or another way